Showing posts with label Financial help. Show all posts

State Of The Art Products: All That Glitters Is Not Gold

Images insurance
Companies compete seriously to outdo each other with the product that they deem will solve their customers’ problems in the short and long run. The market is bombarded with products of all types with promises overlapping each other of miracles they can do. Words like “revolutionary”, “cutting edge”, “new improved”, “enhanced”, and many other advertising language types are used to entice customers into buying. This is part of the marketing plan of many companies and if carried out consistently, often succeeds in drawing many customers to them. It is common knowledge that no product is perfect, despite all the promises and every product has the potential to lead to an accident, damage, loss or any other negative incident. This is what makes it very important for companies to source for product liability insurance quotes to safeguard themselves and the users of their products.


For many manufacturing companies, this kind of insurance is an excellent investment because it provides protection for hidden defects and flaws in the original design in the production process. It also protects a company from misleading marketing campaigns which tend to over-promise and under-deliver. The costs that people incur when they use the products and incur negative outcomes become the source of many court suits because clients usually want their money back because products did not perform as required. Apart from insurance protection, a company should there be very careful with the claims they make for product quality, handling instructions for safe use and return policy agreements. 


In the beauty industry, customers are much more liable to personal injury and damage. This is because, beauty therapy like hair care, skin and body treatment, body enhancements, massages and many other types of personal care services are performed directly on the customer’s person. This is a riskier kind of business because the service provider has to rely on their customer to give them all the information they need to perform their work. Since many customers do not fully know themselves, all kinds of things can happen like allergic reactions, burns, cuts, bleeding and other negative outcomes during the course of their personal care. Without the encompassing protection of beauty therapy insurance, a personal care service provider leaves themselves wide open to all kinds of litigation from furious customers.  

Stories abound of beauty treatments gone badly. Many times this damage is temporary and can be rectified, however, other times the damage causes permanent scarring and disability, loss of hearing in one or both ears, loss of sight in one or both eyes, damage to vital organs like the kidneys or liver from chemicals used, disfiguring of body parts and breakage of limbs, among many other side effects.  Although a personal care service provider may go the extra mile in providing trained personnel to handle client issues, insurance is the best option for those unforeseen eventualities that tend to crop up just when things look like they are getting better.

Financial Wisdom in Medical Insurance

In this day and age, some prudent reluctance when it comes to spending is only to be expected from most people, especially if they have a family to care for. But no matter how much people might like to keep money in their savings account, the issue of possible medical expenses should not be ignored either. Someday, someone will get sick or injured which could drain you of all your savings. As such, paying for something like Medical Insurance would be a far better deal than having to shoulder all the burden of medical expenses later on.

So what is Medical Insurance?

When put in a broad perspective, Medical Insurance is simply the means by which you can protect yourself and your family from any financial trouble that would arise due to expenses incurred by medical issues. How the policy would accomplish this depends on the scenario, but having medical coverage will certainly help in a lot of ways which we will get into further along.Suffice it to say, Medical Insurance is incredibly important if you want to avoid substantial damage in case major medical procedures become necessary.

What are the uses of Medical Insurance?

Now to be more specific, Medical Insurance accomplishes its uses in a variety of ways, but in all of them it basically acts as a safeguard against financial damages or as an assurance of financial capability. For the more well-known example, we have the much needed surgical procedures which involve quite a lot of money. On their own, the medical expenses for this kind of service would be enough to devastate most people financially. With a policy for medical coverage though, the fallout is not as painful. 

Medical Insurance

For another big benefit of having medical coverage, we have hospital admittance. Although it may not be pleasant to hear, the medical industry seems to have become rather obsessed with money of late and people have more of a chance to get admitted into hospitals and gain access to their best services if they are covered. Things that are often taken for granted like staff attention and prioritization are also easier to obtain if you have medical coverage. 

Check-up prospects are also greatly enhanced when you have medical insurance because you would then be more thoroughly inspected for debilitating diseases. This allows you to take better care of yourself if a problem is detected sooner which translates to better survivability. Such a service is not available to everybody since the procedures involved in careful examinations often make use of rather sophisticated and expensive machinery. 

Finally, the services of health professionals are also more easily rendered if you have medical coverage since a policy marks you as a client who has the ability to settle their bills. Such a statement is not meant to sow resentment towards good doctors since such an example does not extend to all of them, but it is also a fact that their services are not always theirs to dispense. It is also a fact that patients have a far greater chance at recovery and survival if they have a specialist monitoring their situation closely.

Considerable Cautions While Opting a Financial Loan

Sometimes at some part of our lives we face financial problems. You may fall short of cash to meet our needs and wants like paying our monthly bills, medical bills, buying a car or home. To fulfil our needs and wants we look for sources which offer financial support. Loans are one of the best sources which assist you financially to achieve your goal. However you need to be very careful and consider certain points when choosing which loans to go for.


`Financial Loans

First of all determine which type of loan will suit your needs. If you require small amounts of money then you can go for short term loans. If you need instant cash then you can opt for paydayloans. If you want to finance for a new home then you can opt for long term mortgage loans. Taking a long term loan for smaller requirements does not make a sense. So, determine your needs and choose accordingly. 

Consider the loans with lower interest rates. Don’t ever consider loans with high interest rates for a small advantage that they are easily approved. If you do so, you will end up paying much more on top of what you owe. Invest some time and effort on shopping around for the best deal. 

Banks and lenders use different types of terminology in calculating the interest rate. So, before considering a particular lender, it is advisable to clearly know the terminology used to calculate the interest rate of the loan.
Check out the additional rates imposed on the borrower. Some banks and financial institutions collect about 2% on the total loan amount as the processing and administrative charges. If the charges imposed are high then the loan burden increases. Some lenders give exemption on these charges. So consider such lenders to reduce your loan burden.

Make sure that the lender is deciding your monthly instalment amount of the loan based on your income. If the lender decides a high monthly payment then you may not be able to pay. If the EMI is less than the duration of the loan term extends and you end up paying much more in the form of interest. So, make sure that the lender determines reasonable monthly payments which allow you to keep up without much difficulty.
Some banks collect charges when you repay the loan amount prior to its due date. They charge about 5% on the loan amount as prepayment charges. So, it is better to find out these things before you apply for the loan.
Ensure that all the details are mentioned in the agreement. Don’t accept the details or promises which are given orally. Today most lenders are present online. With some research online you can find the best lender available to you.  

Commercial Policy for Your Work Vehicle


Whether you're delivering pizzas, hauling materials or chauffeuring clients, you may need to use your vehicle daily as part of your job. What you may not realize is that this use of your car has an effect on your auto insurance policy. Your risk category is higher when you use a car for business purposes, meaning that your rates will be higher than if you drove for pleasure alone. Moreover, insurance companies may deny claims for accidents that happen when the car is used for business purposes.

How Risk Categories Affect Insurance Prices

Insurers determine how much to charge for a policy by assessing a driver's risk. As a rule, people who spend more time behind the wheel will pay more for insurance because they're exposed to the most possible crashes. This means that drivers who commute to work pay more for insurance than those who work from home, and people who use their cars for business pay more than those who don't. 

For many business uses, a personal insurance policy will be insufficient. For example, if you're a delivery driver, your insurance company may deny an accident that occurs while making a delivery. This can put you and your employer at risk of costly lawsuits. Many employers do not provide ample insurance to cover your vehicle, so it's important to do your own research and purchase a policy that will handle your car's business usage. 

Even more importantly, your insurance company may cancel your policy entirely if they realize that you're using the car for business purposes. This may occur between policy terms or after a claim has been filed. Once the policy has been cancelled, it will be harder to find an affordable carrier. It's much better to be up-front with your insurer and see what options are available for commercial coverage rather than taking the risk of losing insurance due to business use.  

Yvttk_2b

Buying Commercial Car Insurance

Many private insurers provide commercial auto policies for business vehicles. Your current carrier may even be able to convert your existing policy to a commercial account with minimal cost difference. Though you may be a high risk as a private driver, you'll be very low risk compared to other commercial customers, so you might qualify for fresh discounts. Be sure to review the coverages carefully and only get the protection that you need since not all coverages will apply to small-scale business usage. 

Before buying a commercial policy, be sure to discuss your options with your current insurer. Your agent will be able to review your specific situation and decide whether you really need a business policy or not. If so, he or she can write a new policy or refer you to a company that can provide coverage. You can also comparison shop online for commercial auto insurance rates to find a new provider. 

Mandi Mangleson lives and writes in London. She writes for www.carinsurance.org.uk where you can find more information on car insurance, trips, and tips for saving money when you drive.

How to Pay Bills while Broke

Knowing how to pay bills when there is no money left can be unpleasant and stressful, if no plan is made.  As late fees appear, you could face legal action against you and loss of assets. In dire financial situations, it is imperative to prioritize payments and check options.

You should think carefully about paying bills while broke and talk directly to your creditors. Learn how to pay bills when little or no money is available after expenses.

Make Paying Bills a Top Priority

Prioritizing bill payments should be your first step. Decide which is the most important bill that you must pay like utilities. Consider which services, if unpaid, would have the biggest impact on your lifestyle. For example, unpaid bills for credit cards can amount to late fees and bad credit records, but usually will not make you lose any assets like defaulting on mortgage payments.

Paying the bills


Consider goods or services that you can live without like Cable TV, gym memberships, magazine subscriptions, and expensive roaming plans. Check all service contracts and payment plans to know if any could be cut or dropped. Lowering or dropping some services may assist you in finding the necessary money to cover bills.

Make a budget with only needed goods and services. Ask friends or family for feedback on your budget to get a second perspective on where else money can be saved.

Negotiate with Your Creditors

It is imperative to communicate with your lenders if payments cannot be made. For example, if you lose your employment or suffer a financial hardship, contact lenders for possible payment arrangements or extensions. Lenders might be willing to assist you if contacted before multiple missed payments accumulate. For example, credit card companies might negotiate a new payment rate based on your current finances. Utility providers could provide advice about programs and agencies that help people pay their bills when financial trouble arises. Certain service providers may even waive early penalty charges.

Avoid ignoring bills, which can lead to bigger problems. If you communicate with your creditors, there is a chance you can have your payments temporarily reduced or deferred for later dates.

Income vs. Savings

Increase money available to pay bills by earning more money or reducing expenses. You should decide which expenses to reduce or remove. The remainder of your regular spending should be determined. After the least necessary expenses have been removed from your budget, use the available money to pay necessary bills. Search for extra ways to become more efficient like reducing power bills by using energy saving devices only. Any money that is saved should be used to pay bills.

If you find that you do not have enough money to pay your bills, there are many resources and options for you. Make a budget to manage bills based on your income and communicate with lenders to know your options. Improve your financial situation by reducing expenses and deciding which bills to pay first while broke. Once you have managed to pay your bills, create an emergency fund to avoid falling into the same financial situation.

This article is provided courtesy of Credit Season UK, a consumer finance website providing information and tools on payday loans and other personal credit services.

Find the Cheapest Car Insurance


With the struggling economy, you might find yourself needing to find ways to save money. One way that you can save money is with the cost of insurance. All of us need insurance; however, you do not need to pay a fortune for your insurance needs. Here are five tips to find cheap insurance.

1. Increase your Credit Score: 

You should ask for a copy of your free credit report and make sure that it is correct. If you have any unpaid bills, make sure you get them paid, and start making payments in a timely manner. You should also try to lower the amount of debt that you have. This can save you lots of money on insurance premiums.

2. Shop Around: 

One of the best ways to find cheap insurance is to compare different companies. Insurance companies are very competitive, so you should shop around for the best rate. You might even have the power to negotiate and get a better rate. Most insurance companies will give you free quotes, so it is a good idea to request at least three quotes and compare prices.

cheapest car insurance

3. No Deposit Car Insurance: 

Car insurance companies are very competitive; many are now offering no deposit car insurance. You will not fact a penalty for making monthly payments instead of one lump sum. Your car insurance payment will be divided into 12 months. If you are strapped for cash, this is a good option.

4. Increase your Deductible: 

You can lower your monthly payments if you increase your deductible. By increasing your deductible, you can save as much as 30 per cent on insurance. However, you want to make sure that you can cover the cost before your deductible is met.

5. Consolidate Policies: 

You can save money by combining your life, health, car and home insurance into one policy. Many people think that they do not need life insurance; however, the cost of a funeral and burial can really be a burden to your loved ones, so it is imperative that you have life insurance. Health and home insurance are also important for you to have, so you will not be stuck with huge bills. By combining policies with the same provider, you can save thousands of dollars.

My name is Patrick and I’m guest blogging for www.carinsurancewithnodeposit.co.uk.

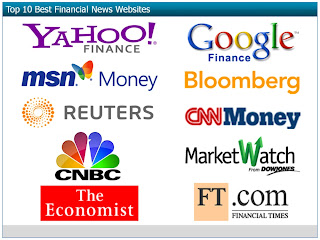
Top 5 Best Finance Websites For You

Keeping up with the world of finance can be difficult with all of the information that is available out there. If you are interested in finance, there are several websites that you can check regularly to stay up to date with what is going on in the world. Here are five of the best finance websites for you to bookmark.

CNN Money 

 CNN Money is one of the most well-known finance websites out there. It is updated throughout the day with contributions from experts in their respective fields. They get content from Fortune, Money, and of course, CNN. They have information about the stock market, banking, bonds, real estate, insurance, and a lot more. 

Investopedia 

Investopedia is one of the best finance websites online. It has a plethora of information about anything that is related to investing. You can get definitions of terms that you understand. You can find articles from investment experts that provide you with tips and strategies. They also provide up-to-date market analysis articles that help you figure out exactly what to do with your portfolio. If you have any questions about investing, this is one of the places that you need to go. 

Best Finance Websites

The Motley Fool 

The Motley Fool is perhaps the most entertaining finance website in the industry. They take a lighthearted approach to analyzing the financial markets and distributing news. Their writers are very knowledgeable, but they also have a good sense of humor. If you don't like the straightforward manner that comes with most of the other finance websites out there, this is definitely one that can keep you interested. They have updated news articles daily, and they also have columns from regular contributors throughout the week. 

Mint 

Mint is a finance website that makes it possible for you to stick to a budget for once. Many people have problems tracking their finances and sticking to a specific budget amount on a regular basis. With Mint, you can set up an account and tie it to all of your other financial accounts online. For example, you can tie it to your checking account, your savings account, credit card accounts and your mortgage. It will update all of your financial accounts regularly so that you can see exactly where you stand. You can set budgets, and then when you make a purchase, it will be deducted from the appropriate spending category in the system. This allows you to see exactly how much you have left at any given time. 

Kiplinger 

Kiplinger is another well-known site in the financial realm. It provides information about investments and recent news events. It also has a section specifically designed for beginners who need to learn the basics of finances.

Sharon Dyer is the Morgan Law Firm Outreach Director and a frequent blogger on a variety of subjects. See her recent article on Travis County divorce on the firm's divorce blog.

How to Dispute Discrepancies on Your Credit Report

Your credit report is one of the most important documents in determining your financial standing. A good credit report can help you achieve your financial goals, purchase valuable assets, and qualify for competitive interest rates on new lines of credit. A bad credit report can keep you from purchasing a new home or car, as well as preventing you from qualifying for credit at low interest rates. This makes it essential to know what’s in your credit report and what you can do to improve your credit by reviewing your credit file regularly.

According to a study released on Bankrate.com, a startling 70 percent of all credit reports contain serious errors or discrepancies which can affect an individual’s credit rating. These include having accounts listed twice, incorrect account statuses, discrepancies on the date penalties were incurred, and even the assignment of incorrect aliases that aren’t the same person. Each of these mistakes can cause decreases in your credit rating and affect your ability to borrow at competitive rates.

By Federal law, every U.S. resident is allowed a free copy of their credit report each year. You can get your free reports by going to annualcreditreport.com and following the instructions to get each of your reports. Keep in mind, your free credit report actually includes the three different variations since you get a different report from each of the three main credit bureaus. Each of the three bureaus—Experian, Equifax, and TransUnion—has their own credit reporting system so they maintain their own version of your credit file. If you want to improve your credit, it’s important to check all three reports.

Credit Report


Once you receive copies of each of your reports, the next step is to carefully review the information included therein. Here are some tips of what you want to look for if you’re trying to find discrepancies:

Check your contact information, paying special attention to any aliases the report indicates are you. In most cases these will be variations of your name, but in some instances the credit bureau will incorrectly assign an alias that’s not actually you.
Check the status of each credit account. Make sure current accounts are showing current on your credit report. For delinquent accounts or any penalties incurred from delinquency or litigation make sure the date the penalty was incurred is correct.
Check to make sure your accounts are only listed once, since double listed accounts increase your total debt load. Total debt owed is a major determining factor in FICO credit scores, so a mortgage listed twice can cause serious damage to your credit.

If you find any errors or discrepancies, submit your request for correction in writing to each of the three credit bureaus. It’s important to send the correction to all three agencies, since they’re not required to communicate with each other. Always submit disputes in writing and keep copies of all correspondence. Keep your explanations brief and to-the-point, and you’ll also want to provide copies of any proof or documentation you have. 

Once you submit your corrections, the credit bureaus will communicate the disputes to all of your relevant creditors. They will have an opportunity to confirm or deny your dispute. If the dispute is confirmed as an error, your report gets corrected and you must be notified if the correction gets rejected or changed at a later time. If you are denied a correction, you are allowed by law to present a summary of your side on the dispute in writing to be included in your credit file.

Even after you correct any errors in your credit reports with the three credit bureaus, you may not have the credit scores you had hoped to see. The credit history listed in your credit report is a main determining factor in your credit scores, but it is not the only piece of your credit puzzle. Total debt owed is another major determining factor. In this light, if correcting discrepancies doesn’t deliver the result you want, your best bet is to find ways to improve your credit history and pay off your debt as quickly as possible. If you need help, contact a non-profit credit counseling agency to allow a certified credit counselor to assess your debts and provide recommendations to help you improve your situation.  

Connie Solidad has been writing about finances and debt consolidation for years. She's an expert in the industry and writes about debt incurred from credit cards, debt management options and credit counseling. When Connie is not working, she loves playing with her two dogs in Tampa, Florida. To learn more about debt management refer to ConsolidatedCredit.org.

How to Secure Online Payday Loans

Payday loans occur with several names like the cash advance loan, payday advances, payroll advances, salary advances and so on. Irrespective of the names, it cannot be argued that the usefulness payday cash offers as a short-term loan until the next paycheck. Especially when an unexpected expense pops up such as car repairs, medical bills or other expenses, a cash advance can help close the gap between salaries.

Most people understand the benefits of these loans since they are: quick, secured and an easy way to get the money you need to cover any unexpected expenses of life. But is it easy to apply for an online payday loans? Or is it safe to give personal details for an online money loan? 

Learn how to safely apply for a fast payday loan online.

If you ask whether it is safe to apply for payday loans online? The answer would be, yes and their reply time? well it depends on which company you use. Most companies offer an online payday loan that assures total security of your personal data. It is seriously considered since the reputation invested by the customer in a company can falter if there is no reliability or safety in the data securement causing a quick loss in the business. As protected as it may seem, here are some tips to ensure that your information is secured when applying for a payday loan online:

1. First, check the privacy policy of any payday lender or broker's website. The privacy policy should be clearly mentioned and it should detail the type of information collected and disseminated to third parties.

 2. If you have questions about site security or the security of your personal information, talk to a customer service representative of the company. Ask questions like: Are databases accessible by all employees or only with security clearances? What happens to the information after you close your account? And based on the answers, make your decision. Make use of a FAQ section (frequently asked questions) that can answer most of your queries.

loans images

3. Once you are satisfied that the site will not tamper with your personal information, verify if the application page is safe. Whenever you transmit sensitive data online, which can be for a payday loan or any transaction, there are two things to consider. The first is an added "s" after the "http" line in the internet address of your browser. The second thing to look for is a yellow padlock symbol in the bottom right of the screen. Both indicate that data is encrypted before being transmitted to the website, and ensures that your information is sent to the respective place.

4. Finally it is vital to investigate the lender of an online payday loan and check if your data is safe. Google their name online or check with the Business Investigation Bureau to see if they have any customer complaints against them. It is always good to see what other people have to say about the company you're about to do business with.

If you are ordering a pizza, buying new clothes, or request a cash advance online, no matter what business you do online, it is important to ensure that your information is secure. By using the above suggestions, you can ensure that the cash advance transaction is secure online.

Steps in Setting up A Bank Account in Cyprus

Those who are planning to open a bank account in Cyprus due to the many financial benefits it provides will be happier learning that the steps in setting up an individual or a corporate bank account are so much easier. Just follow these step by step instructions and you will soon find yourself with all the documents listing all of the necessary bank information for your self or your corporation.

Individual Requirements to Open a Cyprus Bank Account

Anyone, resident or non-resident, that is of the age of 18 is allowed to open a Cyprus bank account. You just need to present a copy of your passport, an accomplished legal due diligence form, and a utility bill that will indicate your address to the bank in order to process your request. After submitting these documents, you may immediately get the bank details you will need for business transactions including your account number, IBAN no., and swift no.

Corporate Requirements to Open a Cyprus Bank Account

For corporations, you need to submit a set of company formation certificates aside from the following documents required for the bank signatories:
1.    certified copy of pages of their valid passport showing the signature, personal details, and photo of the signatories
2.    proof of residential address of the signatory
3.    bank reference letter that has been issued for no less than six months

Cyprus Bank Account

Aside from these, the specimen signature card signed by the signatories that has been certified by the bank’s branch has to be forwarded for the processing of the proper documents. Although the processing of the application does not require personal visits and it can be handled by an authorized representative of the corporation, the directors and signatories still need to visit the bank representative for interview.  In like manner, this will be the perfect opportunity for the bank officer to certify all the personal documents of the mentioned corporate officers.

Regular Banking Hours in Cyprus

Most of the banks operate from 8:30 to 12:30 in the morning and 3:15 to 6:45 in the evening during summer. Nevertheless, individual and corporate bank account are given .Cyprus online banking services for additional convenience. This will allow corporate officers to perform all of their transactions online after providing them with a password that will give access to their account.

Online Banking Services Offered by Cyprus Banks

The following are list of the bank services offered by Cyprus Banks to their clients:
a.    international wire transfer payments
b.    access to account transactions and account balances
c.    bank transfer from an affiliate bank to another

Additional Benefits of a Corporate Bank Account

Aside from these additional conveniences, you will be provided with these additional benefits:
a.  Multi currency account that allows you to deposit in Euro, USD, Swiss Franc and other currencies
b.  Choice of debit, credit, or checking account
c.  Digipass feature, which allows money transfer from your Cyprus bank account to a third party with guaranteed online security

Oxford Tax Solutions provides affordable tax consultations related to international tax issues combined with effective vehicles that will help your investment achieve tax minimization.

Telltale Signs of a Dishonest Bondsman

You know what they say -- don't drink and drive. Unfortunately, not all people follow this very simple rule and they go ahead and drive while under the influence of alcohol. If they get pulled over by the police, they find themselves spending the night in jail.

If you happen to land in prison for a drunk driving incident, then the one thing going through your head is how to get out of jail fast. After all, who wants to spend a night in prison?

Getting Out of Jail

The most common way to get out of jail is to post a bail, the amount of which is set by the judge. If you have money or credit card and if you have a good credit history, then you can quickly get out of jail. If not, then you might have to spend the night in jail until you come up with the bail amount.

Fortunately, getting out of prison is made easier by a bondsman. What they do is to post a bail on your behalf or sign an agreement with the court that you'll be appearing for all the court dates. If you attended all your court dates, the bondsman will get his money back, if he fronted the money, that is. On the other hand, if you skipped bail and did not attend all your court dates, then the court will go after the bondsman, who will have to pay for the whole bail amount. If this happens, the bondsman can set bounty hunters after you to get his money back.

Bondsman

Looking for a Bondsman

If you don't have the money to post a bail, then you have no other choice but to look for a bondsman. However, there are just so many of them to choose from, all of whom are after your business. After all, he is going to earn at least 10% of your bail bond amount, and this is a nonrefundable fee even if you showed up for all your court dates.

Choosing a bondsman is difficult, especially if this is your first time to use their service. For this reason, here are the warning signs of a deceitful bondsman that you should be aware of:
  • You should be extra careful of a bondsman or a bail bond company that advertises zero down and 5% bail. More often than not, they are making use of the "bait and switch" strategy. Yes, the fee is rather small, but you should know they are probably only advertising this low because they want you to sign the contract, and when they get what they want, then they'll tell you the real terms and conditions of their contract. 
  • You should be wary of new bail bond companies, especially those that have no bail bond insurance. You also have to be wary of bondsmen and bail bond agencies whose insurance companies disallowed them from having an outstanding bond liability. More often than not, they're only after your bond money. They'll look for a reason to return you back to jail and have the bond revoked. Some new bail bond companies are also fly-by-night agencies. Once you've paid the premium, they disappear.
  • A bondsman who insists that you sign the contract first before he answers your questions is a sign of a deceitful bondsman, so is a bondsman who is impatient and refuses or avoids to answer your questions. He is more interested in getting your money than helping you out of jail.
Jennifer Dane works for a San Diego bail bonds company. She's also a blogger who owns a couple of blogs that focus mainly on drunk driving as well as bail and bail bonds. Jennifer also contributes articles to Direct, bail bonds company in CA.

Understanding Mortgage Life & Mortgage Disability Insurance

When purchasing a new home, buyers must decide if they want mortgage life insurance and mortgage disability insurance. Both forms of coverage provide some degree of protection if the purchasers become disabled, become terminally ill or die. It is important to know what options are available before deciding. The following points define the various options for both insurances.

1. Reducing Term Mortgage Life Insurance

In the past, this was the most popular type of coverage chosen. The amount owed on the mortgage is the insurance amount, and the death benefit decreases each year as the mortgage is paid down. If the policyholder died suddenly, the remaining amount would be enough to pay off the home. This reduces the chance that the insurance company would pay out more than necessary. For example, they would not want to pay $250,000 to survivors if the current amount owed was only $50,000.

Me and Amy at our new house!!!

2. Term Life Insurance Mortgage Protection

As a rule, this economical form of coverage is the most popular choice today. With this form of coverage, two basic elements are combined: Term life insurance and mortgage payments. This policy offers the same protection as a regular life insurance policy. There is no decreasing benefit over time. However, the term expires when the mortgage is paid in full, which means the policy serves its purpose for the time needed.

3. Return Of Premium Mortgage Life Insurance

This form of coverage comes with higher premiums than regular term life. However, the main advantage is very clear. If the policy is effective throughout the entire term, all premiums paid are returned to the policyholder. In a way, it is similar to simply making a large refundable deposit in multiple installments.

4. Mortgage Disability Insurance

The disability coverage on a mortgage-based policy is somewhat different than regular disability coverage. There are more limitations, and the benefits can only be used to make mortgage payments. For example, with regular disability coverage, the policyholder has the freedom to use the benefit funds to pay for any necessary expenses. Food, medical care and utility bills can be paid. However, mortgage disability benefits are paid directly to the lender. This ensures that the funds are used only for their intended purpose. Keep in mind that most regular disability policies offer between 40 percent and 80 percent of total income replacement. Having a mortgage disability policy to close the gap and ensure a place to live is definitely beneficial. Research shows that a large percentage of foreclosures are due to people becoming disabled and not being able to make mortgage payments. If an individual does not have separate disability coverage, this mortgage policy can be very helpful.

Every home buyer must decide whether these insurance policies are right for their individual needs. It is also important to read the terms of each policy carefully. Not all underwriters have the same requirements or provisions, so be sure to compare quotes and terms before making a final decision.

Andrew Greene is a freelance insurance writer who blogs for ppiclaims.org.uk, a site he recommends to anyone who wants to learn more about ppi claims.

Five Tips to Choosing the Best Home Loan

Buying a house is a major decision, and obtaining a home loan can be a complicated and stressful process. Because the housing industry has expanded so much over time, the lending services offered to home buyers have grown increasingly complex. To avoid being left in the dark or otherwise feeling like you’ve lost control of the process, check out these five tips that will help ease the stress of choosing the right home loan for you and your family.

1. Understand your finances – Before going into any lending situation, it’s extremely important to know how much you can pay for a home. Purchasing a house you cannot afford runs the risk of foreclosure so choose the house you can afford now rather than the one you think you can afford later and borrow accordingly.

Know your credit score, reduce your debt – Knowing your credit score is crucial to this process because the score indicates how much you’ll be lent and the interest rate. There are plenty of free credit report offers and it’s in your best interest to take advantage of them. Similarly, the way to increase your credit score is to reduce your debt. You want to go into this process as close to debt-free as you can to receive the lowest interest rate possible.

3. Research different types of loans – Go in confident by understanding the different types of loans that a particular lender offers. Similarly, be aware of the different fees and penalties that different lenders charge, such as late fees and closing costs.

4. Be wary of the cheapest option – This concerns fixed versus adjustable rate mortgages. A fixed rate may not the be cheapest option at the time, but it’s fixed meaning that it won’t change. An adjustable rate mortgage is only fixed for a certain period of time and then is ‘adjusted’ sometimes as often as monthly.

5. Utilize online comparison websites –There are several mortgage lending sites online that ask basic questions about your yearly income, the size of the home you want, and so forth. These sites will provide a realistic idea of the type of home you can afford and what your payments will be like if you decide on this home or that. Choose a rate and payment schedule you’re comfortable with.

Generally speaking, choosing the home loan that suits you best comes down to understanding your finances as thoroughly as possible. And like any other product you purchase, researching ahead of time is always a smart move. Know your finances, know your lender, and go into this process confident and as worry-free as possible.

Northwest Georgia Bank is a leading Chattanooga bank that offers Chattanooga loans and Chattanooga mortgages with an unbeatable level of customer service.

Steps To Take To Develop Money-Saving Habits

People aren't born from birth to be savers. It takes time to develop money-saving habits. Follow these tips and you'll be saving hundreds of dollars a month in no time.

Budgeting

The first thing you need to do before you can develop your money-saving habits is to decide realistically how much you can save. To accomplish this, you must first devise a budget that lays out all the money you earn and your essential spending. This tells you how much discretionary income you have that you could be saving.

Don't Pay Too Much

The first money-saving habit you should develop is a paranoia about prices. Assume you are paying too much for everything from groceries to car insurance. Then test that assumption. Go to online price comparison sites to see if you can get lower prices on insurance, loan rates, rates for TV, Internet and phone service, and many other services and products. If you can get a lower rate, don't be shy about switching, as long as the new product or service meets your needs. Make sure to take advantage of any chance to lower your prices. This includes bundling insurance policies and cable, TV and Internet services to get discounts.


Spend Money to Save Money

Making impulse purchases is not a good thing, but that doesn't mean its always bad to buy more than you need. If your local supermarket is having a huge sale on products you need and use regularly, buy large amounts and stock them away for future use. If you have a freezer or extra refrigerator, you can buy large amounts of meat and vegetables when they are on sale and freeze them for later use. You can compound your savings by using
supermarket coupons or vouchers during these sales. When buying clothes and shoes for your kids, take advantage of really good sales by buying extra items in larger sizes for use a year or two down the road.

Don't Be Brand Conscious

The best savers out there don't get hung up on the names on their labels. To save money, buy the store brand for food and household purchases. And stay away from designer clothes and shoes. Most of the time they are not better quality than off-brands, they simply cost more because of their name.

Don't Pay for Something You Can Get for Free

If you like to read books, get them from your public library instead of buying them. Read newspapers and magazines online instead of paying for subscriptions. Trade services with friends and neighbors.

These are just a few of the ways you can get started on your way to becoming a saver. There are many more. Follow as many steps as you can and you'll be a much richer person.

How to get a 100% home loan

How to get a 100 % home loan? This a question that many would like to here the answer to. Is there really such a thing? Is there even just a small percentage of a possibility that the answer to this mythical question could be a positive one? To understand more on how to get a 100% home loan we must first understand the facts behind this so-called witches brew for the new families of tomorrow.

Banks, this is the first word that would also play the most important role in your quest of finding the holy grail to a 100% percent home loan. Banks offer a lot of different plans to help you achieve that house that you always wanted. Most often than not if you have a stable income you will be granted a housing loan applicable to your monthly salary capability. Interest, accrued payments and monthly amortizations are all part of the formula. But is getting a 100% home loan part of the banks plan in pursuing your hard earned salary. Hate to burst your bubble but almost 90% of the world’s banks in different counties would say it is impossible. There is no such loan nowadays in the U.S. and neighboring countries by banks alike that would give you a 100% home loan, with no down payment and collateral required.


Banks have reviewed the possibility of giving 100% home loans to their clients time and time again, and as the ball goes around the answer always came to same old conclusion. The banks would be at a loss if ever they implement such a risky deal on their part. There are a few banks that practice the 80-90% rule when it comes to home loans. This means that they are willing to lend you 80-90 % of the loan to value ratio (LVR) provided that you have a stable flow of income. Still this means that the client will be needing to shoulder the remaining 20 or 10 percent from his own savings.

Now you would ask me I mentioned only 90% percent of banks worldwide will not allow you this kind of loan, what about the remaining 10 percent? The best answer to this question is Australia. Why Australia you ask? There are still some banks and real estate lenders down there that would offer you 90 – 95% loan able value in regards to LVR. Still not the 100% value that we all are looking for, but it is surely the closest you can get to acquisition of the reality. You just have to look really hard for legitimate banks and real estate lenders.

The next time you ask the question of “How to get a 100% home loan?” with no strings attached, you might as well kiss your dreams goodbye. The banks don’t see this as a possibility unless you have tons of collateral which will still end up as down payment to that home you always wanted. There is no such thing as 100% free nowadays, but there is something called hard work and savings; and maybe the next best thing “Australia”.

Thinking of Starting a Business – Think Capital Allowances

Since 2008 when the economic climate changed a lot of people have seen the entrepreneurial side to themselves rise to the surface and used this time as an opportunity to start their own business. There are many considerations you will need to look into when deciding if this is the right option for you with money usually being a fairly big consideration.

A recent study showed that few people knew what capital allowances were or understood them, when starting a business it is a good idea to familiarise yourself with incentives available such as capital allowances and tax relief and how your start up could benefit. As capital allowances can offer up to £100,000.00 of tax relief in the first year.


Firstly let’s look at what capital allowances are and who is eligible for them :-

When a business is thinking of investing in an asset, which can vary depending on the industry, but the overall areas to look at are:-

Enhanced capital allowances – environmental based tax relief.

Disposal of assets
Acquiring new assets
Ongoing fixed assets

They may be able to claim capital allowances (tax relief) to reduce the financial burden for the company, which early on in a company’s life can help the business grow, develop and be competitive.


Capital allowances, as the recent study demonstrated are a fairly complex subject and having an
understanding of how your business could benefit requires specialist knowledge to your specific situation and requirements together with looking at your specific investments/assets.

Also it is worth pointing out that from April 2012 the tax relief currently available is significantly reduced from £100,000.00 to £25,000.00.

At any time a business should be aware of when it can benefit financially and in this case from tax relief and capital allowances it should look at the above areas and identify whether any assets they have fall into these areas.

Chris Simons recently decided to set up his own business and found the possibility of capital allowances and tax relief to be a huge financial relief.

4 Smart Decisions that Save on Car Insurance

The high cost of getting and keeping up with auto insurance can be a big hit on anyone’s budget. Fortunately, for anyone in the car insurance market there are a lot of different ways to save on this insurance. Follow these four tips to start saving hundreds of dollars a year.

1. Start your search for insurance by shopping around.

Be sure to compare car insurance prices at several different auto insurance companies. During your search, you’ll probably realize that car insurance rates can vary a lot between companies. In addition to just the normal market differences, auto insurance companies typically vary their rates based on a variety of factors, all of which differ among different companies. For example, the driver’s age and gender can be among the biggest factors in determining someone’s premium at one company, while another company may give more weight to a person’s driving history. Additionally, credit history and where the car is kept at night are also used by some companies to determine premiums.


2. Explore the possibility of bundling your insurance policies.

Many auto insurance companies offer their most significant discounts to customers who have more than one policy with them. This can mean insuring multiple cars, or switching over policies such as homeowner’s, life, or renter’s insurance to your auto insurance company.

3. Ask about how increasing your deductible could save you money.

With many companies, increasing a deductible by as little as $500 can save a consumer a lot of money on their premium. This lower cost to the consumer is a result of the insurance company decreasing their liability. Of course, it is critical to make sure that you have enough cash in a savings account to make up the difference for a higher deductible in the case of an accident. In general, though, since it is likely that you would not claim small damage amounts to your vehicle, increasing your deductible won’t really affect your budget much.

4. Finally, ask your insurer about discounts you already qualify for or could start doing.

Many insurance companies will offer their clients discounts for a variety of safe and normal activities. For example, auto insurance companies currently offer discounts to their customers who regularly wear a seatbelt, have a car alarm system installed in their vehicle, have airbags installed in their car, change their oil on a regular basis, and/or are considered by their state licensing board to be good drivers.

Saving on car insurance doesn't have to be an annoying nag by commercial after commercial. It can be achieved in these four simple steps with the added comfort of saving online.


Author Bio: Brittney L. is a freelance writer and car insurance expert. She enjoys traveling the New England area with her husband and compares travel car insurance rates online to help save money.

Getting Started in Forex Trading


Read on for 3 great tips to help you getting started in forex trading and well on your way to becoming a successful foreign exchange trader.

1)      Before you enter a market, you need to know your market 

Think of the world of forex as a virtual casino. What’s the first thing you do upon entering a casino for the first time? You assess the behavior of each of the tables before placing a bet, so you have a good idea of what sorts of odds you are facing and become aware of any potential high-risk and high-loss games, as well as those with potential high-winnings to be had.   It’s much the same with the foreign currency markets; some currencies are volatile while others ensure solid returns. You should study the forex market and get a feel for patterns and stay ahead of market activity by reading the financial news, keeping a wide-angle view of international news and their economic consequences on the currency market.


Pick a currency pair that suits your trading hours 

Your success as a currency trader is of course dependent on skill and chance, but there are some choices you make that can heavily influence the tenor of your trading volume. If you know you are only available to trade during certain hours, perhaps because of other commitments such as a “day job” or childcare duties, select the currencies that are open during the hours of your trading session so that you are able to follow the movements of that pair as and when it happens, rather than relying purely on advanced trading and risky predictive strategies for currencies whose trading sessions will be open once you have stopped trading for the day.
3)      
Limit your exposure to risk

Apply effective stopping measures to control your risk exposure. By having a watchful eye and implementing practical risk limitation measures, you are doing the smartest thing a trader can do to protect profits and minimize loss. Two examples: Position Sizing; this is a strategy which varies trade sizes according to the current trend; and Stop Placement; this marries indicators to stop loss placement and uses the two in tandem.

Rick Silver is a Financial Writer and contributor to Everest Forex. She spent many years working at leading U.S. investment firms and banks, within the fields of foreign exchange, commodities, structured finance, asset finance and corporate finance.

How to Save Money While Attending College

College is pricey. From costly textbooks to the constant hikes in tuition rates, going to college requires a significant financial investment. The prospects of a good career ahead of you should make this investment worthwhile, but you still won’t want to graduate with astronomical debt. An overwhelming amount of debt can haunt you for decades and some people never manage to fully pay it off. 

Truth be told, college is more expensive than ever before. However, the good news is that there are many simple ways you can save money and still get a great education. By incorporating just a few money saving tips and adjustments into your lifestyle you will be able to make big savings.

Here are a few of our top tips for saving money while attending college:

Go Online

You won’t get the exciting social life you will likely find at a traditional brick and mortar school, but studying online will definitely save you a lot of money! An online university degree program generally offers significantly lower tuition rates in comparison to regular four-year schools. What’s more, you won’t have to re-locate or have to commute to class. Many of your textbooks will likely be downloadable and thus more affordable as well. Furthermore, many online degrees allow you to make your own hours and study at your own pace, so you can easily still hold down your regular day job while you study online!


Look for Grants and Scholarships

Most schools offer substantial amounts of grants and scholarships which essentially equates to free money for the awarded students. Explore any grants and scholarships available and also look into needs-benefits such as veterans education benefits. If you have difficulty understanding what benefits are available to you, most schools have representatives at their financial aid office that can assist you and walk you through the process of applying for grants and any benefits you may be entitled to.


Buy Secondhand

Aside from tuition and accommodation, perhaps the next most expensive aspect of college is textbooks. Buying textbooks brand new can prove to be extremely expensive, so you may want to buy secondhand when you can. Many campus bookstores sell used copies of books as well as new ones and often the used ones are significantly cheaper. In addition, you can usually find even cheaper secondhand books for sale online and there are even online stores where you can rent books per semester. Therefore, always look for potential secondhand copies when possible.

Attend Community College

We all want to go to a prestigious school, but you may want to try attending a community college at first and transferring to your dream school later. Virtually all universities accept transfer students from community colleges and in some cases it has even been reported that it is easier to transfer to a prestigious school as a community college student than it is to get accepted as a freshmen. Community colleges generally offer very affordable course rates and classes can be surprisingly small. You can also find them in all major towns and cities, so you can probably remain living at home which likely means paying no rent!


Prepare for Your Future Career

You are more likely to be crushed by college debt if you are unable to get a solid job shortly after graduation. Interest rates will start to gather and if you are unemployed or earning minimum wage you will unlikely be able to pay your debts back anytime soon. However, there are various ways you can prepare yourself for a prosperous and financially rewarding career while you are still in college. One excellent way to prepare yourself is to complete several internships while in college. Employers are always impressed if you have real world work experience and internships also allow you to build up contacts that you can call upon when you are looking for work as well as for references in the future.  

As you can see, college doesn’t have to completely drain your financial resources. It is pretty likely that you will graduate with some level of debt, but this debt doesn’t have to be crippling if you make wise financial decisions while in college. Whether you decide to attend an online university or simply only buy secondhand books the savings you will accumulate have the potential to help you stay further out of the red. Be cautious with your spending and always keep an eye out for thrifty ways to complete your education. Good luck! 

What to Do Should Your Insurance Claim Ever be Denied


Insurance is such a strange product in that you buy it hoping you never have to use it, sort of like a fire extinguisher. However, unlike a fire extinguisher you can’t just take your home insurance policy out into the yard and play with it on a whim. It’s devastating then if your property is damaged and the insurance you were otherwise relying on denies your claim. That there even is the perennial joke that insurance companies are tight-fisted indicates that claim denials are common enough, so what do you do when you’re claims denied—certainly not roll over (at least not yet anyway).


Make Sure You Understand Your Policy

Before ever leaving you insurance agent’s office, make sure you understand the details of the product you are buying. It can be difficult to ask specific questions, so instead simply tell your agent when you don’t fully comprehend anything. Equally feel free to take notes. Naturally you are going to forget exactly what the policy says, but you’ll have a more substantial gist of what you are entitled to. Now when your property is stolen or damaged take a little bit of time to review your policy (assuming it hasn’t been destroyed) so that when you do contact your insurance you have not only had a refresher course on your policy, but you are able to describe the nature of your claim in the context of your policy.

Contact Your Agent

Before making your claim officially, be sure to discuss it with your insurance agent. On some policies there are serious repercussions for making a claim and being denied. For example you can lose your no-claims bonus, which is worth it if you have to rebuild your home—but certainly not worth it if your insurance agent thinks that a denial is unavoidable.


Keep a Paper Trail

In the event your claim is denied make sure you receive proper documentation along with an explanation of the reasons for denial. This will make the process of checking the denial against the actual terms of your policy infinitely easier. Equally make sure you document the costs of all out-of-pocket costs including, repairs, nights in a hotel, rental cars etc. Though requiring a bit of foresight, keeping close records of preventative maintenance and the like can help disprove accusations of policy violations.

Appeal

The numbers appear to indicate that only about 1% of denials are ever appealed—and half of appeals see some sort of relief from their insurers. Fill out the appeal using the explanation of denial and your policy to set forth a cogent rebuttal.

Lawyer Up, Contact a third-party Agent 

Should your appeal be rejected, there are private insurance agents out there who will assess the damage and your claim independently and will give you some sort of realistic grounding as to the viability of suing your insurance company. Equally, there are lawyers who also specialize in this sort of litigation, lawyers who will also likely be open to free consultations to discuss your claim against your insurance company. Though be aware that litigation can often take years to produce any results, so if you have gotten to this point be prepared for a long fight.