Insolvency and UK’s Battle Against Debt

The credit crisis that currently grips the UK shows no sign of abating and the sheer size of debt in the country is astronomical. Insolvency numbers are expected to rise as debt levels have tripled over the last decade. Licensed insolvency practitioners are preparing to help thousands of struggling people solve their debt problems.

The current financial state of the UK doesn’t make pleasant viewing and it is affecting consumers up and down the country. Insolvency levels are fully expected to reach record highs this year and a report has shown that young people are amongst the most financially vulnerable in the UK due to the level of debt that they have accrued.

Insolvency – The debt cycle

Financial experts often suggest that an individual voluntary arrangement is a good way for people with high levels of debt to tackle their problems. Debt problems in the UK are getting to the stage where the threat of insolvency or bankruptcy looms large over a vast proportion of the population. The studies conducted by building societies discovered that apart from rent and mortgages, interest upon debts has become the largest single outgoing for those under 35. This invariably leads to spiralling debts and insolvency may occur for many who find repayments impossible. However, those within the financial industry have seen individual voluntary arrangements successfully guide many away from the precipice of debt.
Debt Images

The credit card culture of consumers in the UK has seen levels of debt reach unsustainable levels. The financial fallout from this will be record numbers of insolvency in 2012 as people struggle to stay on top of their finances and become unable to meet the repayments demanded by their creditors. In many cases, individuals will opt for an individual voluntary arrangement (IVA) in order to solve their monetary woes and stave off the threat of insolvency.

Insolvency – A Numbers Game

The sheer scale of debt in the UK is testament to the spending culture of Briton’s and has reached a point at which it becomes impossible for the lending to continue in such an unrestricted manner. By the end of the second quarter of 2007, the size of consumer debt in the UK was an unprecedented £1.345 trillion, which outstripped the annual gross domestic product by some £15 billion. This financial discrepancy will have the effect of increasing the number of insolvency cases in the UK as people can no longer sustain their spending levels. An IVA is often utilised by those in debt as it can ward off the threat of bankruptcy and it is a legally binding contract between the individual and their creditors to pay back their debt at a level within their means.

Insolvency – Taking Financial Risks

The levels of debt in the UK and the way in which people spend at a level beyond their means is causing a massive debt gulf which will swallow a record number this year as insolvency levels are set to skyrocket. Speaking to the Daily Mail, Mark Allen, a financial expert spoke of the precarious situation of people’s personal finance, “It's not uncommon these days to see some individuals with unsecured debt upwards of £50,000 spread across four or five credit cards and a mortgage on top of that. These people are balancing on a perilous tightrope”. As insolvency levels reach record levels, the numbers who see an individual voluntary arrangement as the ideal solution to their debt woes is likely to increase exponentially and many will return to financial security as a result.

Younger borrowers turn to reverse mortgages

According to recent reports, a large number of young homeowners are turning to reverse mortgages as they’re experiencing a huge increase in their unsecured debt levels. Reverse mortgage loans are the best financing options for the seniors who live on a fixed income level and need immediate cash for home renovation or any other purpose. Studies suggest that the previous borrowers of the reverse mortgage loans used them to improve their home, their biggest asset, but now the younger borrowers are taking resort to the reverse mortgage loans in order to meet their pressing financial needs. No amount of professional debt settlement advice can aid the young borrowers get out of debt. 

The reverse mortgage loans are actually tailored to meet the need of the seniors above 62 years of age. The government issues all reverse mortgages to the seniors through the HECM or the Home Equity Conversion Mortgage program and through this the senior can access the cash that he has accumulated as equity in his home and receive regular monthly payments from the lender. The reverse mortgage program is usually considered as the most exotic product for the seniors but the recent study shows that the borrowers of this kind of loan are those who are about to enter the retirement age and they all are taking out such loans in order to control their soaring household debt burden. It isn’t a far-fetched fact that the close-to-retirement-aged people are considering reverse mortgages as most of them have grown up managing their financial debt and according to them reverse mortgages give them the chance to facilitate their monthly repayment structure. 

reverse mortgages

Are reverse mortgages cheap products? 

The fees and the interest rates that are associated with reverse mortgages that were there in 1999 made such mortgage programs prohibitive to the mortgage programs and it is since then that the US Department of Education and the HUD or the Housing and Urban Development stepped in to make these cheaper and affordable for the seniors of the US who are suffering financially. This made the HECM saver the ultimate product for all those who are looking for a reasonable mortgage to repay their soaring debt obligations. 

The HECM has a few disadvantages for the younger borrowers as the young people may expect less cash or lower monthly payments than their older counterparts. According to a survey by MetLife, one in four baby boomers seeks reverse mortgage loans when they have subsequent amount of debt. All those belonging to the “sandwich generation” may find themselves in dire financial straits when they don’t take out a reverse mortgage to meet the needs. They can stop running to the debt help companies if they’re sure about the reverse mortgage program.

Myrina Stein is a regular writer for various finance related Communities including Oak View Law Group and CDFA. She is a Post Graduate degree holder in Finance from a reputed University in California and right now working in a Finance Consultancy as a Project Manager. She is well equipped to write articles on debt consolidation , debt settlement advice, bankruptcy, credit problems etc

Find the Cheapest Car Insurance


With the struggling economy, you might find yourself needing to find ways to save money. One way that you can save money is with the cost of insurance. All of us need insurance; however, you do not need to pay a fortune for your insurance needs. Here are five tips to find cheap insurance.

1. Increase your Credit Score: 

You should ask for a copy of your free credit report and make sure that it is correct. If you have any unpaid bills, make sure you get them paid, and start making payments in a timely manner. You should also try to lower the amount of debt that you have. This can save you lots of money on insurance premiums.

2. Shop Around: 

One of the best ways to find cheap insurance is to compare different companies. Insurance companies are very competitive, so you should shop around for the best rate. You might even have the power to negotiate and get a better rate. Most insurance companies will give you free quotes, so it is a good idea to request at least three quotes and compare prices.

cheapest car insurance

3. No Deposit Car Insurance: 

Car insurance companies are very competitive; many are now offering no deposit car insurance. You will not fact a penalty for making monthly payments instead of one lump sum. Your car insurance payment will be divided into 12 months. If you are strapped for cash, this is a good option.

4. Increase your Deductible: 

You can lower your monthly payments if you increase your deductible. By increasing your deductible, you can save as much as 30 per cent on insurance. However, you want to make sure that you can cover the cost before your deductible is met.

5. Consolidate Policies: 

You can save money by combining your life, health, car and home insurance into one policy. Many people think that they do not need life insurance; however, the cost of a funeral and burial can really be a burden to your loved ones, so it is imperative that you have life insurance. Health and home insurance are also important for you to have, so you will not be stuck with huge bills. By combining policies with the same provider, you can save thousands of dollars.

My name is Patrick and I’m guest blogging for www.carinsurancewithnodeposit.co.uk.

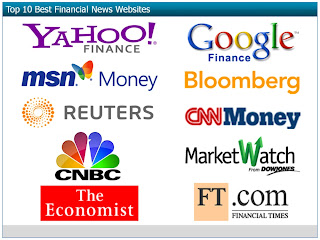
Top 5 Best Finance Websites For You

Keeping up with the world of finance can be difficult with all of the information that is available out there. If you are interested in finance, there are several websites that you can check regularly to stay up to date with what is going on in the world. Here are five of the best finance websites for you to bookmark.

CNN Money 

 CNN Money is one of the most well-known finance websites out there. It is updated throughout the day with contributions from experts in their respective fields. They get content from Fortune, Money, and of course, CNN. They have information about the stock market, banking, bonds, real estate, insurance, and a lot more. 

Investopedia 

Investopedia is one of the best finance websites online. It has a plethora of information about anything that is related to investing. You can get definitions of terms that you understand. You can find articles from investment experts that provide you with tips and strategies. They also provide up-to-date market analysis articles that help you figure out exactly what to do with your portfolio. If you have any questions about investing, this is one of the places that you need to go. 

Best Finance Websites

The Motley Fool 

The Motley Fool is perhaps the most entertaining finance website in the industry. They take a lighthearted approach to analyzing the financial markets and distributing news. Their writers are very knowledgeable, but they also have a good sense of humor. If you don't like the straightforward manner that comes with most of the other finance websites out there, this is definitely one that can keep you interested. They have updated news articles daily, and they also have columns from regular contributors throughout the week. 

Mint 

Mint is a finance website that makes it possible for you to stick to a budget for once. Many people have problems tracking their finances and sticking to a specific budget amount on a regular basis. With Mint, you can set up an account and tie it to all of your other financial accounts online. For example, you can tie it to your checking account, your savings account, credit card accounts and your mortgage. It will update all of your financial accounts regularly so that you can see exactly where you stand. You can set budgets, and then when you make a purchase, it will be deducted from the appropriate spending category in the system. This allows you to see exactly how much you have left at any given time. 

Kiplinger 

Kiplinger is another well-known site in the financial realm. It provides information about investments and recent news events. It also has a section specifically designed for beginners who need to learn the basics of finances.

Sharon Dyer is the Morgan Law Firm Outreach Director and a frequent blogger on a variety of subjects. See her recent article on Travis County divorce on the firm's divorce blog.

How to Dispute Discrepancies on Your Credit Report

Your credit report is one of the most important documents in determining your financial standing. A good credit report can help you achieve your financial goals, purchase valuable assets, and qualify for competitive interest rates on new lines of credit. A bad credit report can keep you from purchasing a new home or car, as well as preventing you from qualifying for credit at low interest rates. This makes it essential to know what’s in your credit report and what you can do to improve your credit by reviewing your credit file regularly.

According to a study released on Bankrate.com, a startling 70 percent of all credit reports contain serious errors or discrepancies which can affect an individual’s credit rating. These include having accounts listed twice, incorrect account statuses, discrepancies on the date penalties were incurred, and even the assignment of incorrect aliases that aren’t the same person. Each of these mistakes can cause decreases in your credit rating and affect your ability to borrow at competitive rates.

By Federal law, every U.S. resident is allowed a free copy of their credit report each year. You can get your free reports by going to annualcreditreport.com and following the instructions to get each of your reports. Keep in mind, your free credit report actually includes the three different variations since you get a different report from each of the three main credit bureaus. Each of the three bureaus—Experian, Equifax, and TransUnion—has their own credit reporting system so they maintain their own version of your credit file. If you want to improve your credit, it’s important to check all three reports.

Credit Report


Once you receive copies of each of your reports, the next step is to carefully review the information included therein. Here are some tips of what you want to look for if you’re trying to find discrepancies:

• Check your contact information, paying special attention to any aliases the report indicates are you. In most cases these will be variations of your name, but in some instances the credit bureau will incorrectly assign an alias that’s not actually you.
• Check the status of each credit account. Make sure current accounts are showing current on your credit report. For delinquent accounts or any penalties incurred from delinquency or litigation make sure the date the penalty was incurred is correct.
• Check to make sure your accounts are only listed once, since double listed accounts increase your total debt load. Total debt owed is a major determining factor in FICO credit scores, so a mortgage listed twice can cause serious damage to your credit.

If you find any errors or discrepancies, submit your request for correction in writing to each of the three credit bureaus. It’s important to send the correction to all three agencies, since they’re not required to communicate with each other. Always submit disputes in writing and keep copies of all correspondence. Keep your explanations brief and to-the-point, and you’ll also want to provide copies of any proof or documentation you have. 

Once you submit your corrections, the credit bureaus will communicate the disputes to all of your relevant creditors. They will have an opportunity to confirm or deny your dispute. If the dispute is confirmed as an error, your report gets corrected and you must be notified if the correction gets rejected or changed at a later time. If you are denied a correction, you are allowed by law to present a summary of your side on the dispute in writing to be included in your credit file.

Even after you correct any errors in your credit reports with the three credit bureaus, you may not have the credit scores you had hoped to see. The credit history listed in your credit report is a main determining factor in your credit scores, but it is not the only piece of your credit puzzle. Total debt owed is another major determining factor. In this light, if correcting discrepancies doesn’t deliver the result you want, your best bet is to find ways to improve your credit history and pay off your debt as quickly as possible. If you need help, contact a non-profit credit counseling agency to allow a certified credit counselor to assess your debts and provide recommendations to help you improve your situation.  

Connie Solidad has been writing about finances and debt consolidation for years. She's an expert in the industry and writes about debt incurred from credit cards, debt management options and credit counseling. When Connie is not working, she loves playing with her two dogs in Tampa, Florida. To learn more about debt management refer to ConsolidatedCredit.org.

How to Secure Online Payday Loans

Payday loans occur with several names like the cash advance loan, payday advances, payroll advances, salary advances and so on. Irrespective of the names, it cannot be argued that the usefulness payday cash offers as a short-term loan until the next paycheck. Especially when an unexpected expense pops up such as car repairs, medical bills or other expenses, a cash advance can help close the gap between salaries.

Most people understand the benefits of these loans since they are: quick, secured and an easy way to get the money you need to cover any unexpected expenses of life. But is it easy to apply for an online payday loans? Or is it safe to give personal details for an online money loan? 

Learn how to safely apply for a fast payday loan online.

If you ask whether it is safe to apply for payday loans online? The answer would be, yes and their reply time? well it depends on which company you use. Most companies offer an online payday loan that assures total security of your personal data. It is seriously considered since the reputation invested by the customer in a company can falter if there is no reliability or safety in the data securement causing a quick loss in the business. As protected as it may seem, here are some tips to ensure that your information is secured when applying for a payday loan online:

1. First, check the privacy policy of any payday lender or broker's website. The privacy policy should be clearly mentioned and it should detail the type of information collected and disseminated to third parties.

 2. If you have questions about site security or the security of your personal information, talk to a customer service representative of the company. Ask questions like: Are databases accessible by all employees or only with security clearances? What happens to the information after you close your account? And based on the answers, make your decision. Make use of a FAQ section (frequently asked questions) that can answer most of your queries.

loans images

3. Once you are satisfied that the site will not tamper with your personal information, verify if the application page is safe. Whenever you transmit sensitive data online, which can be for a payday loan or any transaction, there are two things to consider. The first is an added "s" after the "http" line in the internet address of your browser. The second thing to look for is a yellow padlock symbol in the bottom right of the screen. Both indicate that data is encrypted before being transmitted to the website, and ensures that your information is sent to the respective place.

4. Finally it is vital to investigate the lender of an online payday loan and check if your data is safe. Google their name online or check with the Business Investigation Bureau to see if they have any customer complaints against them. It is always good to see what other people have to say about the company you're about to do business with.

If you are ordering a pizza, buying new clothes, or request a cash advance online, no matter what business you do online, it is important to ensure that your information is secure. By using the above suggestions, you can ensure that the cash advance transaction is secure online.

Steps in Setting up A Bank Account in Cyprus

Those who are planning to open a bank account in Cyprus due to the many financial benefits it provides will be happier learning that the steps in setting up an individual or a corporate bank account are so much easier. Just follow these step by step instructions and you will soon find yourself with all the documents listing all of the necessary bank information for your self or your corporation.

Individual Requirements to Open a Cyprus Bank Account

Anyone, resident or non-resident, that is of the age of 18 is allowed to open a Cyprus bank account. You just need to present a copy of your passport, an accomplished legal due diligence form, and a utility bill that will indicate your address to the bank in order to process your request. After submitting these documents, you may immediately get the bank details you will need for business transactions including your account number, IBAN no., and swift no.

Corporate Requirements to Open a Cyprus Bank Account

For corporations, you need to submit a set of company formation certificates aside from the following documents required for the bank signatories:
1.    certified copy of pages of their valid passport showing the signature, personal details, and photo of the signatories
2.    proof of residential address of the signatory
3.    bank reference letter that has been issued for no less than six months

Cyprus Bank Account

Aside from these, the specimen signature card signed by the signatories that has been certified by the bank’s branch has to be forwarded for the processing of the proper documents. Although the processing of the application does not require personal visits and it can be handled by an authorized representative of the corporation, the directors and signatories still need to visit the bank representative for interview.  In like manner, this will be the perfect opportunity for the bank officer to certify all the personal documents of the mentioned corporate officers.

Regular Banking Hours in Cyprus

Most of the banks operate from 8:30 to 12:30 in the morning and 3:15 to 6:45 in the evening during summer. Nevertheless, individual and corporate bank account are given .Cyprus online banking services for additional convenience. This will allow corporate officers to perform all of their transactions online after providing them with a password that will give access to their account.

Online Banking Services Offered by Cyprus Banks

The following are list of the bank services offered by Cyprus Banks to their clients:
a.    international wire transfer payments
b.    access to account transactions and account balances
c.    bank transfer from an affiliate bank to another

Additional Benefits of a Corporate Bank Account

Aside from these additional conveniences, you will be provided with these additional benefits:
a.  Multi currency account that allows you to deposit in Euro, USD, Swiss Franc and other currencies
b.  Choice of debit, credit, or checking account
c.  Digipass feature, which allows money transfer from your Cyprus bank account to a third party with guaranteed online security

Oxford Tax Solutions provides affordable tax consultations related to international tax issues combined with effective vehicles that will help your investment achieve tax minimization.

Telltale Signs of a Dishonest Bondsman

You know what they say -- don't drink and drive. Unfortunately, not all people follow this very simple rule and they go ahead and drive while under the influence of alcohol. If they get pulled over by the police, they find themselves spending the night in jail.

If you happen to land in prison for a drunk driving incident, then the one thing going through your head is how to get out of jail fast. After all, who wants to spend a night in prison?

Getting Out of Jail

The most common way to get out of jail is to post a bail, the amount of which is set by the judge. If you have money or credit card and if you have a good credit history, then you can quickly get out of jail. If not, then you might have to spend the night in jail until you come up with the bail amount.

Fortunately, getting out of prison is made easier by a bondsman. What they do is to post a bail on your behalf or sign an agreement with the court that you'll be appearing for all the court dates. If you attended all your court dates, the bondsman will get his money back, if he fronted the money, that is. On the other hand, if you skipped bail and did not attend all your court dates, then the court will go after the bondsman, who will have to pay for the whole bail amount. If this happens, the bondsman can set bounty hunters after you to get his money back.

Bondsman

Looking for a Bondsman

If you don't have the money to post a bail, then you have no other choice but to look for a bondsman. However, there are just so many of them to choose from, all of whom are after your business. After all, he is going to earn at least 10% of your bail bond amount, and this is a nonrefundable fee even if you showed up for all your court dates.

Choosing a bondsman is difficult, especially if this is your first time to use their service. For this reason, here are the warning signs of a deceitful bondsman that you should be aware of:
  • You should be extra careful of a bondsman or a bail bond company that advertises zero down and 5% bail. More often than not, they are making use of the "bait and switch" strategy. Yes, the fee is rather small, but you should know they are probably only advertising this low because they want you to sign the contract, and when they get what they want, then they'll tell you the real terms and conditions of their contract. 
  • You should be wary of new bail bond companies, especially those that have no bail bond insurance. You also have to be wary of bondsmen and bail bond agencies whose insurance companies disallowed them from having an outstanding bond liability. More often than not, they're only after your bond money. They'll look for a reason to return you back to jail and have the bond revoked. Some new bail bond companies are also fly-by-night agencies. Once you've paid the premium, they disappear.
  • A bondsman who insists that you sign the contract first before he answers your questions is a sign of a deceitful bondsman, so is a bondsman who is impatient and refuses or avoids to answer your questions. He is more interested in getting your money than helping you out of jail.
Jennifer Dane works for a San Diego bail bonds company. She's also a blogger who owns a couple of blogs that focus mainly on drunk driving as well as bail and bail bonds. Jennifer also contributes articles to Direct, bail bonds company in CA.

How To Evaluate Auto Insurance Quotes Online

Shopping on the World Wide Web has become a common practice in today's times. Since most people have some sort of daily access to the internet, they can do a lot of purchasing on the Web without actually having to go to a business location. When comparing quotes from different companies online, there are some standard procedures shoppers should follow before making a final purchase.

In order to get the best coverage for the least amount of money, one will need to shop around. Compare prices of at least three vehicle coverage companies. There are even internet sites that will show estimated prices of ten or more policy providers all at one time. This gives the buyer a chance to review costs of multiple providers quickly and without having to go through the trouble of calling each one.

A person should always know what they are buying. Read the fine print and details about policy before purchasing. Be aware of what is covered and how much it is covered for. Pay attention to procedures for filing claims and receiving payouts.

                                            Auto Insurance Quotes images

Another important aspect of buying on the internet is to evaluate the customer support system of a company. This is particularly true if the company is strictly web based. Customers should be able to get a hold of a representative 24 hours a day seven days a week. Car accidents happen at all times of the day and night and when they do, drivers should be able to reach their vehicle coverage company.

Examining auto insurance quotes online means that buyers will need to evaluate a few important aspects. Always get price estimates from at least three providers and know the details about policy specifics. It's imperative that internet vehicle policy shoppers select a company that has a strong customer support system in place. A live representative should be available to customers at all times.

OnlineAutoInsurance.com brings free, fast, unbiased auto insurance quote comparisonsto consumers and helps people save the hassle of getting quotes individually without requiring any personal information or lengthy procedures to find cheap car insurance rates.

Understanding Mortgage Life & Mortgage Disability Insurance

When purchasing a new home, buyers must decide if they want mortgage life insurance and mortgage disability insurance. Both forms of coverage provide some degree of protection if the purchasers become disabled, become terminally ill or die. It is important to know what options are available before deciding. The following points define the various options for both insurances.

1. Reducing Term Mortgage Life Insurance

In the past, this was the most popular type of coverage chosen. The amount owed on the mortgage is the insurance amount, and the death benefit decreases each year as the mortgage is paid down. If the policyholder died suddenly, the remaining amount would be enough to pay off the home. This reduces the chance that the insurance company would pay out more than necessary. For example, they would not want to pay $250,000 to survivors if the current amount owed was only $50,000.

Me and Amy at our new house!!!

2. Term Life Insurance Mortgage Protection

As a rule, this economical form of coverage is the most popular choice today. With this form of coverage, two basic elements are combined: Term life insurance and mortgage payments. This policy offers the same protection as a regular life insurance policy. There is no decreasing benefit over time. However, the term expires when the mortgage is paid in full, which means the policy serves its purpose for the time needed.

3. Return Of Premium Mortgage Life Insurance

This form of coverage comes with higher premiums than regular term life. However, the main advantage is very clear. If the policy is effective throughout the entire term, all premiums paid are returned to the policyholder. In a way, it is similar to simply making a large refundable deposit in multiple installments.

4. Mortgage Disability Insurance

The disability coverage on a mortgage-based policy is somewhat different than regular disability coverage. There are more limitations, and the benefits can only be used to make mortgage payments. For example, with regular disability coverage, the policyholder has the freedom to use the benefit funds to pay for any necessary expenses. Food, medical care and utility bills can be paid. However, mortgage disability benefits are paid directly to the lender. This ensures that the funds are used only for their intended purpose. Keep in mind that most regular disability policies offer between 40 percent and 80 percent of total income replacement. Having a mortgage disability policy to close the gap and ensure a place to live is definitely beneficial. Research shows that a large percentage of foreclosures are due to people becoming disabled and not being able to make mortgage payments. If an individual does not have separate disability coverage, this mortgage policy can be very helpful.

Every home buyer must decide whether these insurance policies are right for their individual needs. It is also important to read the terms of each policy carefully. Not all underwriters have the same requirements or provisions, so be sure to compare quotes and terms before making a final decision.

Andrew Greene is a freelance insurance writer who blogs for ppiclaims.org.uk, a site he recommends to anyone who wants to learn more about ppi claims.

10 Most common insurance myths

Insurance policies have become an important part of life with the increase in risks related to life and accidents. These policies can be very complicated and surrounded with a lot of false information. You must not believe everything you hear, because there are many myths associated with your insurance policies. 

The 10 most common myths are as follows: 

1. Benefits should equal premiums:

 Your policy is your buffer against severe financial problems and not to be used for daily ups and downs in life. You must not feel cheated if you have been paying premium for years and never made a claim. 

 2. Everyone needs life insurance:

For some even this policy is unnecessary. The policy is designed to give financial care to your dependents. This includes your children or any elderly person who depends on you. If you do not have any dependents, then you may not need the policy. 

 3. Only the breadwinner needs to be insured: 

It is generally believed that only the person who earns in the family needs to be insured. We tend to forget that duties such as house care, food preparation etc also must be taken into account. Thus a non-working spouse also contributes greatly to the budget; therefore even he or she should be insured for life.
Car insurance images

 4. Your car not your responsibility if someone else drives it: 

Even if someone else is driving your car and causes an accident, you will be financially held responsible for it. 

 5. No need to insure old cars: 

According to statistical information old cars are the ones that get stolen the most, because it’s easier to steal them. 

6. Company will pay for a rental car if your car gets stolen:

This is not automatically included in your policy. Even if you have comprehensive and collision coverage the policy will not include a rental car. 

7. You need flood coverage only in a high risk area: 

All areas under a National Insurance Program are eligible to buy flood insurance. You must be insured if you live in a flood prone zone. 8. Umbrella insurance is for rich people: As lawsuits occur so commonly now, this policy is for all home, auto and watercraft owners and not just for the wealthy. 

 9. You don’t affect others when you don’t get insured:

 If you decide to be uninsured, you are indirectly affecting the lives of others. This will include the lives of those who are dependent on you. 

10. Red cars increase your policy premium: 

Many drivers think that car color is an important factor when it comes to paying premiums. This is not true at all.

How bad credit can affect your family

Financial indiscretions or poor money decisions affect your future and your family. Making late payments, missing payments, owing high balances or opening multiple credit cards lowers your credit score. Even if you made these mistakes during your college years, negative information remains on your credit report for up to seven years. When future creditors evaluate your credit history, your past mistakes indicate that you are a high credit risk. Creditors may refuse to extend credit to you or may assess high interest rates on new loans. Your family’s finances and future are adversely affected by bad credit.

Bad credit limits your ability to meet your family’s current needs. When you owe money to numerous creditors, you spend your income repaying the debts. You have no excess money to repair the leaking house roof or buy new clothing for your growing children. Your spare money goes toward repaying debt accumulated in the past. You also have access to limited financial resources. Already overextended, new creditors may be reluctant to open new credit cards or offer store credit for essential household expenses.

                                        Family Credit union Images

With poor credit, your family may be unable to obtain affordable housing. If your family expands, your home sustains weather-related damages or elderly parents must move in with you, you could be left without financial resources to purchase a new home or make improvements. Mortgage lenders and property managers perform credit checks on potential buyers. In most cases, they choose to extend credit and favorable interests rates only to the consumers with clean credit records. Poor credit reveals your history of missing payments or paying less than the minimum payment. You may lose valuable housing assistance because of bad credit.

After a vehicular accident, a new baby is born or never ending auto repair bills, you may wish to purchase a different vehicle. Bad credit limits your ability to purchase a reliable vehicle upgrade. While auto dealers advertise loans for consumers with bad credit, the money is not free. You will pay high interest or receive other unfavorable loan arrangements that limit your ability to maintain the payments and stay current on other household expenses.

Repeated phone calls or letters from creditors can lead to emotional stress or depression. Additionally, the weight of unpaid debt strains family relationships. One spouse blames the other for irresponsible spending. The strained relationship inhibits honest communication about a solution, and the debt cycle continues. In many cases, bad credit leads to emotional separation, health problems or divorce. Instead of suffering, work with your spouse to create a solution to your bad credit.

Bad credit indicates the possibility of poor spending habits. Unaddressed, increased spending on credit prevents your family from finding financial freedom. It keeps you stuck repaying creditors for items you probably do not really need.

Learn to live within your means. Record an accurate list of your family’s monthly income and expenses. Look for ways to increase your income, and cut unnecessary expenses. Use the excess money to repay outstanding debts and save an emergency fund. At least once a month, hold a business meeting with your spouse. Address the next month’s bills, and work out a manageable budget. By agreeing together on your financial goals, you improve your credit and protect your family’s financial future.

Has the gold bubble burst?

Fresh fears that the “safe haven” aspect of gold investing could be over hit investors last week with the news as “large institutions” began selling off their gold as February came to an end.
Commentators and financial advisors (as reported by a blogger for The Telegraph) think gold prices have started a downward trend and will eventually dip to around $1,000 per ounce.
This caused gold to dip in price by $100 in less than a day.

Key figures such as Brian Dennehy from Dennehy Weller speculate that there could be a final spike in gold prices and then a “large correction” in the gold price will begin, taking gold down to $1,000 an ounce. He thinks gold could even get as low as $700 an ounce.

Hope for gold prices

Of course, with every financial commentator saying that gold will fall, there is a bullion seller to say that no, the gold market is not over and that any dips in price are only temporary.

Ben Yearsley at Hargreaves Lansdowne says: “The gold price has remained high and gold shares haven’t really moved; therefore the disconnect between their profits and share prices remains.
“The world is still in an uncertain place; therefore the demand for gold will remain strong, underpinning the gold price and underpinning gold miners’ profits. So the outlook for gold shares remains good.”

Sell your gold while you can still profit

So who is right? Is Yearsley right with his optimistic view or is Dennehy right when saying that the boom is over for gold? Whoever is right, the message to investors seems to be very clear: sell, sell and sell some more.

If gold is booming, then selling makes sense; if only to avoid the dramatic fall in price that occurred last September. If gold is about to dip dramatically then the same rule applies. In this financial climate it does not make sense to hold onto a valuable, profitable commodity that changes in price daily.

How to get the best price for gold

Who knows if cash for gold prices will drop suddenly? Current market indications and subsequent research indicate that such a dip could happen. However, with the financial problems of the world still unresolved, gold could still climb back up to that $2,000 per ounce figure or even higher.

If you’re uncertain, and wish to still get a great price for your jewellery, the onus is on you to take control and sell gold now. Don’t wait for the market to change suddenly; which could leave you out of pocket.

Use our excellent gold price comparison service to find the best gold buyers for you.

5 Ways to get the best Hospital Cover Quote

To get the best hospital coverage quote, you need to do some checking of different features. There are 5 great ways you can get the best deals and the coverage that you really need.

#1 Look Online at Sites

When you checkout sites online, you can quickly compare what different hospital coverage plans offers. You can submit your information to get no obligation quotes. You can also see information online that helps you to find out what other companies have to say about a given provider. You can get the pros and cons from those that have had to rely on their services. Make sure you read the fine print too on what they state they offer so that you don’t get mixed up with coverage that is lacking.

#2 Be Honest

Even though you don’t have to do a physical exam to get a hospital plan, you do need to be honest about the information you share. You need to declare any lifestyle choices that you take part in such as drinking or smoking. Be honest about your weight, your physical activity, diet, and any health concerns you may have. You also will be asked about your family history and you should be honest with that information based on the knowledge you currently have.

#3 What is your Budget for the Monthly Price?

You need to know what the amount is you can reasonably pay for each month with your hospital coverage. Try to get a dollar amount that is less than what you can afford to pay. That way you don’t get into a bind where you fall short. Never agree to a price that you can barely afford or that you know will be an ongoing struggle for you. Don’t say you can’t afford any coverage at all though. You need to make more money, cut expenses, and do what you have to so that money is free to pay for this coverage. It is too risky to be without it.

#4 Identify the Coverage you Need

Assess your needs and make sure what you pay for offers you the coverage you need. If the cost is too much, start taking out those coverage elements that are nice to have but not necessary. When you have more money to work with later on, you can increase the amount of coverage that you have. If you are married or you have children, look for coverage that has everyone included, not just you.

#5 Benefit from Discounts and Special Offers

Many of the providers out there are doing all they can to entice people to get their hospital coverage from them and not from a competitor. They offer discounts that allow you to get the coverage you need at a lower price. Look around for such offers so you can stretch the money you do have to pay for your coverage. You can find such offers online but most of them have an expiration date you need to be aware of.

How a Cell Phone Contract Works

You can get a lot of value out of a long-term cell phone contract. Long-term phone contracts provide more than simply a refreshment of minutes every month. Perks include being able to call other members for free who are in contract with the same carrier and free texting , depending on the carrier. In addition, a previously unaffordable cell phone can become affordable if purchased with a contract; it's a lot like the cell phone company is offering you a credit card to purchase the phone. Higher priced phones generally have better parts and are engineered better which allows them to last the duration of long contracts.

You typically do not get phone insurance with pay-as-you-go routes. Also, when you acquire a higher quality phone with more features with a long-term contract, you have a lot of extra time to experiment with extra features far beyond the bounds of the two to four week trial period. Phones are so complex these days that many people feel that trial period is not long enough.

Cell phone contracts also have the benefit of allowing users to track their call usage over a long period of time. This can be an essential component of the relationship between the cell phone company and a consumer who meticulously tracks their own usage to micromanage it. Viewing your usage history in a big picture view gives you the benefit to track such things as trends in your calling. For instance, if your usage becomes free at 7:00pm and you are making a lot of calls beginning at 6:45pm, you can try to train yourself to wait the extra 15 minutes. Long term contracts also provide you with the ability to see just how many text messages you are sending. If you happen to be going over your limit of text messages for the month, and there is no higher package for text messages, and you are finding that you have excess voice minutes remaining at the end of each month, you can opt to phone certain people you text message frequently instead of texting them.

Many people switch to cell phones from landlines. They can get the same reliability a landline provides while having the ability to use the phone wherever they go. It's a great option for those on the go, people on business trips, and for those who are in between homes. A lot of people begin with pay-as-you-go contracts when switching over to cell phones from a landline. This provides them with time to give cell phones a good trial before they commit to something longer term.

So, as you can see, a long-term contract offers a lot of perks that a pay-as-you-go arrangement may not. You typically have better phones to choose from, and added benefits written into the contract such as insurance and customer service over the phone. What's more is that you have statements with detailed phone usage to help you gauge how you should use the phone most wisely in the future. There are a plethora of advantages.

How to Lower Auto Insurance Costs

Is lowering auto insurance costs a move that is worth the effort? Fortunately, you can accomplish that in many ways. Following are some tips that can make you save more money in auto insurance:

Ask Someone to Evaluate You

Let your current provider of auto insurance know if you are satisfied with their services. They will go at lengths to make you stay with them and keep you happy. However, in some cases you may ask them to evaluate your premium anew. Let them know that your driving record is flawless, your credit has improved, and include more stuff that will make them understand that more changes are in order.

Let them know about current life changes too, such as marriage. That is a legitimate ground for evaluation. You can also include someone else in your policy. Making two separate policies won't make much sense when one will do, so it is recommended that you keep the policy that does the best work. There are also auto insurance providers that give married couples discounts.

A significant date, such as a birthday, can also be a good reason for evaluation. For example, insurance costs for 21-year-olds should be smaller than those for 19-year-olds. Having taken any driving lessons can also allow you to garner more discounts. Thus, never forget these events when you are being evaluated.

Go For a Greater Deductible

If you never needed to file an auto insurance claim for long, you will be noticed as a safe driver. Now, you can save money by making the deductible amount greater. The deductible is the money that you pay from your wallet when filing a claim. Though the deductible could be some hundred dollars more than its current amount, it is possible for you to save 15-30% on monthly premiums if you increase your deductible.

Devices that Analyze the Way you Drive

Many providers of car insurance place devices on vehicles of policyholders. The purpose of that is to examine the way you drive for a specified length of time, which could be at least 30 days. With that, you can save money as long as the reports indicate that speeding isn't your thing, you don't make sudden stops, and even if you do not seem like that you drive very long distances with your automobile. You can keep more money in your pocket if you drive 20 miles per day compared to if you drive 50 miles per day.

Snap Off Coverage for Roadside Assistance

In auto insurance, roadside assistance can sound like a brilliant idea. However, if your vehicle is working well, you will need it very, very rarely. So pull out the roadside assistance of your coverage so that you can save money. If you'll ever need help, a tow truck or many other roadside assistance services are only one mobile phone call away. It won't cost that much as you think, and every year, you will end up paying less for them than the amount that you pay for roadside assistance on your coverage.

Five Tips to Choosing the Best Home Loan

Buying a house is a major decision, and obtaining a home loan can be a complicated and stressful process. Because the housing industry has expanded so much over time, the lending services offered to home buyers have grown increasingly complex. To avoid being left in the dark or otherwise feeling like you’ve lost control of the process, check out these five tips that will help ease the stress of choosing the right home loan for you and your family.

1. Understand your finances – Before going into any lending situation, it’s extremely important to know how much you can pay for a home. Purchasing a house you cannot afford runs the risk of foreclosure so choose the house you can afford now rather than the one you think you can afford later and borrow accordingly.

Know your credit score, reduce your debt – Knowing your credit score is crucial to this process because the score indicates how much you’ll be lent and the interest rate. There are plenty of free credit report offers and it’s in your best interest to take advantage of them. Similarly, the way to increase your credit score is to reduce your debt. You want to go into this process as close to debt-free as you can to receive the lowest interest rate possible.

3. Research different types of loans – Go in confident by understanding the different types of loans that a particular lender offers. Similarly, be aware of the different fees and penalties that different lenders charge, such as late fees and closing costs.

4. Be wary of the cheapest option – This concerns fixed versus adjustable rate mortgages. A fixed rate may not the be cheapest option at the time, but it’s fixed meaning that it won’t change. An adjustable rate mortgage is only fixed for a certain period of time and then is ‘adjusted’ sometimes as often as monthly.

5. Utilize online comparison websites –There are several mortgage lending sites online that ask basic questions about your yearly income, the size of the home you want, and so forth. These sites will provide a realistic idea of the type of home you can afford and what your payments will be like if you decide on this home or that. Choose a rate and payment schedule you’re comfortable with.

Generally speaking, choosing the home loan that suits you best comes down to understanding your finances as thoroughly as possible. And like any other product you purchase, researching ahead of time is always a smart move. Know your finances, know your lender, and go into this process confident and as worry-free as possible.

Northwest Georgia Bank is a leading Chattanooga bank that offers Chattanooga loans and Chattanooga mortgages with an unbeatable level of customer service.

Steps To Take To Develop Money-Saving Habits

People aren't born from birth to be savers. It takes time to develop money-saving habits. Follow these tips and you'll be saving hundreds of dollars a month in no time.

Budgeting

The first thing you need to do before you can develop your money-saving habits is to decide realistically how much you can save. To accomplish this, you must first devise a budget that lays out all the money you earn and your essential spending. This tells you how much discretionary income you have that you could be saving.

Don't Pay Too Much

The first money-saving habit you should develop is a paranoia about prices. Assume you are paying too much for everything from groceries to car insurance. Then test that assumption. Go to online price comparison sites to see if you can get lower prices on insurance, loan rates, rates for TV, Internet and phone service, and many other services and products. If you can get a lower rate, don't be shy about switching, as long as the new product or service meets your needs. Make sure to take advantage of any chance to lower your prices. This includes bundling insurance policies and cable, TV and Internet services to get discounts.


Spend Money to Save Money

Making impulse purchases is not a good thing, but that doesn't mean its always bad to buy more than you need. If your local supermarket is having a huge sale on products you need and use regularly, buy large amounts and stock them away for future use. If you have a freezer or extra refrigerator, you can buy large amounts of meat and vegetables when they are on sale and freeze them for later use. You can compound your savings by using
supermarket coupons or vouchers during these sales. When buying clothes and shoes for your kids, take advantage of really good sales by buying extra items in larger sizes for use a year or two down the road.

Don't Be Brand Conscious

The best savers out there don't get hung up on the names on their labels. To save money, buy the store brand for food and household purchases. And stay away from designer clothes and shoes. Most of the time they are not better quality than off-brands, they simply cost more because of their name.

Don't Pay for Something You Can Get for Free

If you like to read books, get them from your public library instead of buying them. Read newspapers and magazines online instead of paying for subscriptions. Trade services with friends and neighbors.

These are just a few of the ways you can get started on your way to becoming a saver. There are many more. Follow as many steps as you can and you'll be a much richer person.

How to get a 100% home loan

How to get a 100 % home loan? This a question that many would like to here the answer to. Is there really such a thing? Is there even just a small percentage of a possibility that the answer to this mythical question could be a positive one? To understand more on how to get a 100% home loan we must first understand the facts behind this so-called witches brew for the new families of tomorrow.

Banks, this is the first word that would also play the most important role in your quest of finding the holy grail to a 100% percent home loan. Banks offer a lot of different plans to help you achieve that house that you always wanted. Most often than not if you have a stable income you will be granted a housing loan applicable to your monthly salary capability. Interest, accrued payments and monthly amortizations are all part of the formula. But is getting a 100% home loan part of the banks plan in pursuing your hard earned salary. Hate to burst your bubble but almost 90% of the world’s banks in different counties would say it is impossible. There is no such loan nowadays in the U.S. and neighboring countries by banks alike that would give you a 100% home loan, with no down payment and collateral required.


Banks have reviewed the possibility of giving 100% home loans to their clients time and time again, and as the ball goes around the answer always came to same old conclusion. The banks would be at a loss if ever they implement such a risky deal on their part. There are a few banks that practice the 80-90% rule when it comes to home loans. This means that they are willing to lend you 80-90 % of the loan to value ratio (LVR) provided that you have a stable flow of income. Still this means that the client will be needing to shoulder the remaining 20 or 10 percent from his own savings.

Now you would ask me I mentioned only 90% percent of banks worldwide will not allow you this kind of loan, what about the remaining 10 percent? The best answer to this question is Australia. Why Australia you ask? There are still some banks and real estate lenders down there that would offer you 90 – 95% loan able value in regards to LVR. Still not the 100% value that we all are looking for, but it is surely the closest you can get to acquisition of the reality. You just have to look really hard for legitimate banks and real estate lenders.

The next time you ask the question of “How to get a 100% home loan?” with no strings attached, you might as well kiss your dreams goodbye. The banks don’t see this as a possibility unless you have tons of collateral which will still end up as down payment to that home you always wanted. There is no such thing as 100% free nowadays, but there is something called hard work and savings; and maybe the next best thing “Australia”.